We will have a mirror site at http://nunezreport.wordpress.com in case we are censored, Please save the link

Tuesday, January 21, 2014

The $23 Trillion Credit Bubble In China Is Starting To Collapse

Bubble - Photo by Jeff Kubina

Did you know that financial institutions all over the world are warning that we could see a "mega default" on a very prominent high-yield investment product in China on January 31st?  We are being told that this could lead to a cascading collapse of the shadow banking system in China which could potentially result in "sky-high interest rates" and "a precipitous plunge in credit".  In other words, it could be a "Lehman Brothers moment" for Asia.  And since the global financial system is more interconnected today than ever before, that would be very bad news for the United States as well.  Since Lehman Brothers collapsed in 2008, the level of private domestic credit in China has risen from $9 trillion to an astounding $23 trillion.  That is an increase of $14 trillion in just a little bit more than 5 years.  Much of that "hot money" has flowed into stocks, bonds and real estate in the United States.  So what do you think is going to happen when that bubble collapses?
The bubble of private debt that we have seen inflate in China since the Lehman crisis is unlike anything that the world has ever seen.  Never before has so much private debt been accumulated in such a short period of time.  All of this debt has helped fuel tremendous economic growth in China, but now a whole bunch of Chinese companies are realizing that they have gotten in way, way over their heads.  In fact, it is being projected that Chinese companies will pay out the equivalent ofapproximately a trillion dollars in interest payments this year alone.  That is more than twice the amount that the U.S. government will pay in interest in 2014.
Over the past several years, the U.S. Federal Reserve, the European Central Bank, the Bank of Japan and the Bank of England have all been criticized for creating too much money.  But the truth is that what has been happening in China surpasses all of their efforts combined.  You can see an incredible chart which graphically illustrates this point right here.  As the Telegraph pointed out a while back, the Chinese have essentially "replicated the entire U.S. commercial banking system" in just five years...
Overall credit has jumped from $9 trillion to $23 trillion since the Lehman crisis. "They have replicated the entire U.S. commercial banking system in five years," she said.
The ratio of credit to GDP has jumped by 75 percentage points to 200pc of GDP, compared to roughly 40 points in the US over five years leading up to the subprime bubble, or in Japan before the Nikkei bubble burst in 1990. "This is beyond anything we have ever seen before in a large economy. We don't know how this will play out. The next six months will be crucial," she said.
As with all other things in the financial world, what goes up must eventually come down.
And right now January 31st is shaping up to be a particularly important day for the Chinese financial system.  The following is from a Reuters article...
The trust firm responsible for a troubled high-yield investment product sold through China's largest banks has warned investors they may not be repaid when the 3 billion-yuan ($496 million)product matures on Jan. 31, state media reported on Friday.
Investors are closely watching the case to see if it will shatter assumptions that the government and state-owned banks will always protect investors from losses on risky off-balance-sheet investment products sold through a murky shadow banking system.
If there is a major default on January 31st, the effects could ripple throughout the entire Chinese financial system very rapidly.  A recent Forbes article explained why this is the case...
A WMP default, whether relating to Liansheng or Zhenfu, could devastate the Chinese banking system and the larger economy as well.  In short, China’s growth since the end of 2008 has been dependent on ultra-loose credit first channeled through state banks, like ICBC and Construction Bank, and then through the WMPs, which permitted the state banks to avoid credit risk.  Any disruption in the flow of cash from investors to dodgy borrowers through WMPs would rock China with sky-high interest rates or a precipitous plunge in credit, probably both.  The result?  The best outcome would be decades of misery, what we saw in Japan after its bubble burst in the early 1990s.
The big underlying problem is the fact that private debt and the money supply have both been growing far too rapidly in China.  According to Forbes, M2 in China increased by 13.6 percent last year...
And at the same time China’s money supply and credit are still expanding.  Last year, the closely watched M2 increased by only 13.6%, down from 2012’s 13.8% growth.  Optimists say China is getting its credit addiction under control, but that’s not correct.  In fact, credit expanded by at least 20% last year as money poured into new channels not measured by traditional statistics.
Overall, M2 in China is up by about 1000 percent since 1999.  That is absolutely insane.
And of course China is not the only place in the world where financial trouble signs are erupting.  Things in Europe just keep getting worse, and we have just learned that the largest bank in Germany just suffered " a surprise fourth-quarter loss"...
Deutsche Bank shares tumbled on Monday following a surprise fourth-quarter loss due to a steep drop in debt trading revenues and heavy litigation and restructuring costs that prompted the bank to warn of a challenging 2014.
Germany's biggest bank said revenue at its important debt-trading division, fell 31 percent in the quarter, a much bigger drop than at U.S. rivals, which have also suffered from sluggish fixed-income trading.
If current trends continue, many other big banks will soon be experiencing a "bond headache" as well.  At this point, Treasury Bond sentiment is about the lowest that it has been in about 20 years.  Investors overwhelmingly believe that yields are heading higher.
If that does indeed turn out to be the case, interest rates throughout our economy are going to be rising, economic activity will start slowing down significantly and it could set up the "nightmare scenario" that I keep talking about.
But I am not the only one talking about it.
In fact, the World Economic Forum is warning about the exact same thing...
Fiscal crises triggered by ballooning debt levels in advanced economies pose the biggest threat to the global economy in 2014, a report by the World Economic Forum has warned.
Ahead of next week's WEF annual meeting in Davos, Switzerland, the forum's annual assessment of global dangers said high levels of debt in advanced economies, including Japan and America, could lead to an investor backlash.
This would create a "vicious cycle" of ballooning interest payments, rising debt piles and investor doubt that would force interest rates up further.
So will a default event in China on January 31st be the next "Lehman Brothers moment" or will it be something else?
In the end, it doesn't really matter.  The truth is that what has been going on in the global financial system is completely and totally unsustainable, and it is inevitable that it is all going to come horribly crashing down at some point during the next few years.
It is just a matter of time.
Credit to Economic Collapse

The Retail Death Rattle


“I was part of that strange race of people aptly described as spending their lives doing things they detest, to make money they don’t want, to buy things they don’t need, to impress people they don’t like.” - Emile Gauvreau
If ever a chart provided unequivocal proof the economic recovery storyline is a fraud, the one below is the smoking gun. November and December retail sales account for 20% to 40% of annual retail sales for most retailers. The number of visits to retail stores has plummeted by 50% since 2010. Please note this was during a supposed economic recovery. Also note consumer spending accounts for 70% of GDP. Also note credit card debt outstanding is 7% lower than its level in 2010 and 16% below its peak in 2008. Retailers like J.C. Penney, Best Buy, Sears, Radio Shack and Barnes & Noble continue to report appalling sales and profit results, along with listings of store closings. Even the heavyweights like Wal-Mart and Target continue to report negative comp store sales. How can the government and mainstream media be reporting an economic recovery when the industry that accounts for 70% of GDP is in free fall? The answer is that 99% of America has not had an economic recovery. Only Bernanke’s 1% owner class have benefited from his QE/ZIRP induced stock market levitation.
The entire economic recovery storyline is a sham built upon easy money funneled by the Fed to the Too Big To Trust Wall Street banks so they can use their HFT supercomputers to drive the stock market higher, buy up the millions of homes they foreclosed upon to artificially drive up home prices, and generate profits through rigging commodity, currency, and bond markets, while reducing loan loss reserves because they are free to value their toxic assets at anything they please – compliments of the spineless nerds at the FASB. GDP has been artificially propped up by the Federal government through the magic of EBT cards, SSDI for the depressed and downtrodden, never ending extensions of unemployment benefits, billions in student loans to University of Phoenix prodigies, and subprime auto loans to deadbeats from the Government Motors financing arm – Ally Financial (85% owned by you the taxpayer). The country is being kept afloat on an ocean of debt and delusional belief in the power of central bankers to steer this ship through a sea of icebergs just below the surface.
The absolute collapse in retail visitor counts is the warning siren that this country is about to collide with the reality Americans have run out of time, money, jobs, and illusions. The most amazingly delusional aspect to the chart above is retailers continued to add 44 million square feet in 2013 to the almost 15 billion existing square feet of retail space in the U.S. That is approximately 47 square feet of retail space for every person in America. Retail CEOs are not the brightest bulbs in the sale bin, as exhibited by the CEO of Target and his gross malfeasance in protecting his customers’ personal financial information. Of course, the 44 million square feet added in 2013 is down 85% from the annual increases from 2000 through 2008. The exponential growth model, built upon a never ending flow of consumer credit and an endless supply of cheap fuel, has reached its limit of growth. The titans of Wall Street and their puppets in Washington D.C. have wrung every drop of faux wealth from the dying middle class. There are nothing left but withering carcasses and bleached bones.
The impact of this retail death spiral will be vast and far reaching. A few factoids will help you understand the coming calamity:
  • There are approximately 109,500 shopping centers in the United States ranging in size from the small convenience centers to the large super-regional malls.
  • There are in excess of 1 million retail establishments in the United States occupying 15 billion square feet of space and generating over $4.4 trillion of annual sales. This includes 8,700 department stores, 160,000 clothing & accessory stores, and 8,600 game stores.
  • U.S. shopping-center retail sales total more than $2.26 trillion, accounting for over half of all retail sales.
  • The U.S. shopping-center industry directly employed over 12 million people in 2010 and indirectly generated another 5.6 million jobs in support industries. Collectively, the industry accounted for 12.7% of total U.S. employment.
  • Total retail employment in 2012 totaled 14.9 million, lower than the 15.1 million employed in 2002.
  • For every 100 individuals directly employed at a U.S. regional shopping center, an additional 20 to 30 jobs are supported in the community due to multiplier effects.
The collapse in foot traffic to the 109,500 shopping centers that crisscross our suburban sprawl paradise of plenty is irreversible.No amount of marketing propaganda, 50% off sales, or hot new iGadgets is going to spur a dramatic turnaround. Quarter after quarter there will be more announcements of store closings. Macys just announced the closing of 5 stores and firing of 2,500 retail workers. JC Penney just announced the closing of 33 stores and firing of 2,000 retail workers. Announcements are imminent from Sears, Radio Shack and a slew of other retailers who are beginning to see the writing on the wall. The vacancy rate will be rising in strip malls, power malls and regional malls, with the largest growing sector being ghost malls. Before long it will appear that SPACE AVAILABLE is the fastest growing retailer in America.
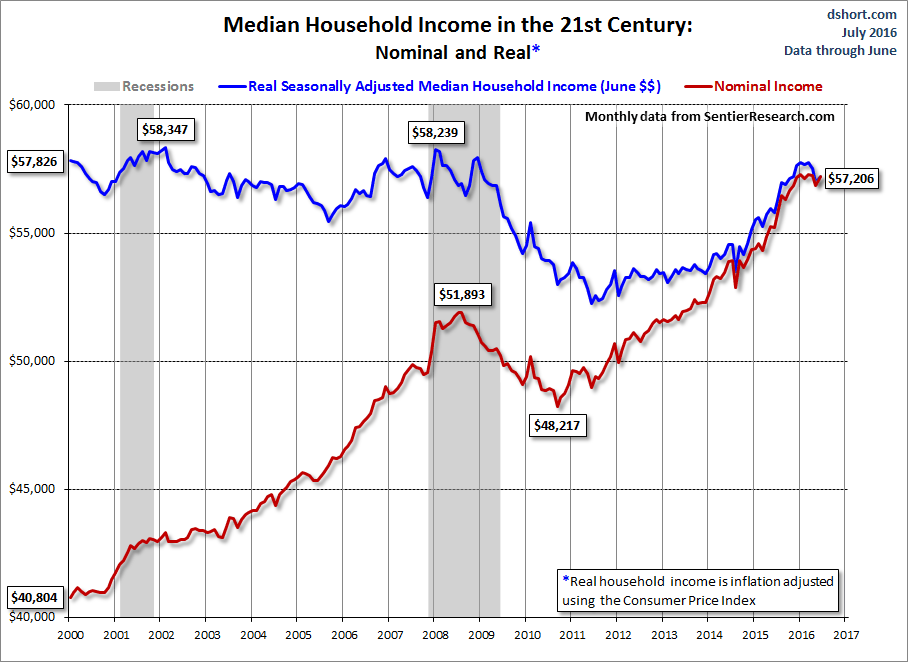
The reason this death spiral cannot be reversed is simply a matter of arithmetic and demographics. While arrogant hubristic retail CEOs of public big box mega-retailers added 2.7 billion retail square feet to our already over saturated market, real median household income flat lined. The advancement in retail spending was attributable solely to the $1.1 trillion increase (68%) in consumer debt and the trillion dollars of home equity extracted from castles in the sky, that later crashed down to earth. Once the Wall Street created fraud collapsed and the waves of delusion subsided, retailers have been revealed to be swimming naked. Their relentless expansion, based on exponential growth, cannibalized itself, new store construction ground to a halt, sales and profits have declined, and the inevitable closing of thousands of stores has begun. With real median household income 8% lower than it was in 2008, the collapse in retail traffic is a rational reaction by the impoverished 99%. Americans are using their credit cards to pay their real estate taxes, income taxes, and monthly utilities, since their income is lower, and their living expenses rise relentlessly, thanks to Bernanke and his Fed created inflation.
The media mouthpieces for the establishment gloss over the fact average gasoline prices in 2013 were the second highest in history. The highest average price was in 2012 and the 3rd highest average price was in 2011. These prices are 150% higher than prices in the early 2000′s. This might not matter to the likes of Jamie Dimon and Jon Corzine, but for a middle class family with two parents working and making 7.5% less than they made in 2000, it has a dramatic impact on discretionary income. The fact oil prices have risen from $25 per barrel in 2003 to $100 per barrel today has not only impacted gas prices, but utility costs, food costs, and the price of any product that needs to be transported to your local Wally World. The outrageous rise in tuition prices has been aided and abetted by the Federal government and their doling out of loans so diploma mills like the University of Phoenix can bilk clueless dupes into thinking they are on their way to an exciting new career, while leaving them jobless in their parents’ basement with a loan payment for life.
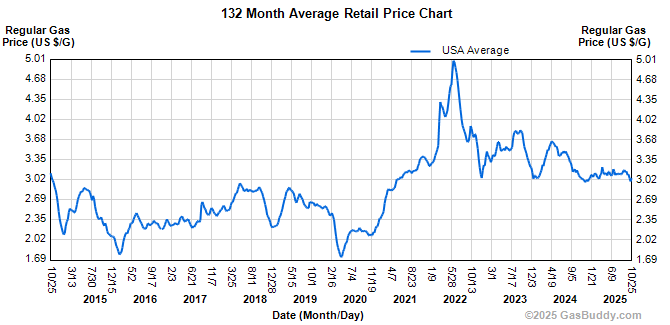
The laughable jobs recovery touted by Obama, his sycophantic minions, paid off economist shills, and the discredited corporate legacy media can be viewed appropriately in the following two charts, that reveal the false storyline being peddled to the techno-narcissistic iGadget distracted masses. There are 247 million working age Americans between the ages of 18 and 64. Only 145 million of these people are employed. Of these employed, 19 million are working part-time and 9 million are self- employed. Another 20 million are employed by the government, producing nothing and being sustained by the few remaining producers with their tax dollars. The labor participation rate is the lowest it has been since women entered the workforce in large numbers during the 1980′s. We are back to levels seen during the booming Carter years. Those peddling the drivel about retiring Baby Boomers causing the decline in the labor participation rate are either math challenged or willfully ignorant because they are being paid to be so. Once you turn 65 you are no longer counted in the work force. The percentage of those over 55 in the workforce has risen dramatically to an all-time high, as the Me Generation never saved for retirement or saw their retirement savings obliterated in the Wall Street created 2008 financial implosion.
To understand the absolute idiocy of retail CEOs across the land one must parse the employment data back to 2000. In the year 2000 the working age population of the U.S. was 213 million and 136.9 million of them were working, a record level of 64.4% of the population. There were 70 million working age Americans not in the labor force. Fourteen years later the number of working age Americans is 247 million and only 144.6 million are working. The working age population has risen by 16% and the number of employed has risen by only 5.6%. That’s quite a success story. Of course, even though median household income is 7.5% lower than it was in 2000, the government expects you to believe that 22 million Americans voluntarily left the labor force because they no longer needed a job. While the number of employed grew by 5.6% over fourteen years, the number of people who left the workforce grew by 31.1%. Over this same time frame the mega-retailers that dominate the landscape added almost 3 billion square feet of selling space, a 25% increase. A critical thinking individual might wonder how this could possibly end well for the retail genius CEOs in glistening corporate office towers from coast to coast.
This entire materialistic orgy of consumerism has been sustained solely with debt peddled by the Wall Street banking syndicate.The average American consumer met their Waterloo in 2008. Bernanke’s mission was to save bankers, billionaires and politicians. It was not to save the working middle class. You’ve been sacrificed at the altar of the .1%. The 0% interest rates were for Jamie Dimon and Lloyd Blankfein. Your credit card interest rate remained between 13% and 21%. So, while you struggle to pay bills with your declining real income, the Wall Street bankers are again generating record profits and paying themselves record bonuses. Profits are so good, they can afford to pay tens of billions in fines for their criminal acts, and still be left with billions to divvy up among their non-prosecuted criminal executives.
Bernanke and his financial elite owners have been able to rig the markets to give the appearance of normalcy, but they cannot rig the demographic time bomb that will cause the death and destruction of our illusory retail paradigm. Demographics cannot be manipulated or altered by the government or mass media. The best they can do is ignore or lie about the facts. The life cycle of a human being is utterly predictable, along with their habits across time. Those under 25 years old have very little income, therefore they have very little spending. Once a job is attained and income levels rise, spending rises along with the increased income. As the person enters old age their income declines and spending on stuff declines rapidly. The media may be ignoring the fact that annual expenditures drop by 40% for those over 65 years old from the peak spending years of 45 to 54, but it doesn’t change the fact. They also cannot change the fact that 10,000 Americans will turn 65 every day for the next sixteen years. They also can’t change the fact the average Baby Boomer has less than $50,000 saved for retirement and is up to their grey eye brows in debt.
With over 15% of all 25 to 34 year olds living in their parents’ basement and those under 25 saddled with billions in student loan debt, the traditional increase in income and spending is DOA for the millennial generation. The hardest hit demographic on the job front during the 2008 through 2014 ongoing recession has been the 45 to 54 year olds in their peak earning and spending years. Combine these demographic developments and you’ve got a perfect storm for over-built retailers and their egotistical CEOs.
The media continues to peddle the storyline of on-line sales saving the ancient bricks and mortar retailers. Again, the talking head pundits are willfully ignoring basic math. On-line sales account for 6% of total retail sales. If a dying behemoth like JC Penney announces a 20% decline in same store sales and a 20% increase in on-line sales, their total change is still negative 17.6%. And they are still left with 1,100 decaying stores, 100,000 employees, lease payments, debt payments, maintenance costs, utility costs, inventory costs, and pension costs. Their future is so bright they gotta wear a toe tag.
The decades of mal-investment in retail stores was enabled by Greenspan, Bernanke, and their Federal Reserve brethren. Their easy money policies enabled Americans to live far beyond their true means through credit card debt, auto debt, mortgage debt, and home equity debt. This false illusion of wealth and foolish spending led mega-retailers to ignore facts and spread like locusts across the suburban countryside. The debt fueled orgy has run out of steam. All that is left is the largest mountain of debt in human history, a gutted and debt laden former middle class, and thousands of empty stores in future decaying ghost malls haunting the highways and byways of suburbia.
The implications of this long and winding road to ruin are far reaching. Store closings so far have only been a ripple compared to the tsunami coming to right size the industry for a future of declining spending. Over the next five to ten years, tens of thousands of stores will be shuttered. Companies like JC Penney, Sears and Radio Shack will go bankrupt and become historical footnotes. Considering retail employment is lower today than it was in 2002 before the massive retail expansion, the future will see in excess of 1 million retail workers lose their jobs. Bernanke and the Feds have allowed real estate mall owners to roll over non-performing loans and pretend they are generating enough rental income to cover their loan obligations. As more stores go dark, this little game of extend and pretend will come to an end. Real estate developers will be going belly-up and the banking sector will be taking huge losses again. I’m sure the remaining taxpayers will gladly bailout Wall Street again. The facts are not debatable. They can be ignored by the politicians, Ivy League economists, media talking heads, and the willfully ignorant masses, but they do not cease to exist.
“Facts do not cease to exist because they are ignored.” –Aldous Huxley
Credit to Zero Hedge 
Monday, January 20, 2014

Eurozone stress test could show over US$1 trillion shortfall in banks


An objective stress test of the eurozone’s biggest banks could reveal a capital shortfall of more than 770 billion euros (US$1 trillion) and trigger further public bailouts, a study by an adviser to the European Union’s financial risk watchdog and a Berlin academic has found.

The study and others published ahead of the EU stress tests, whose results are due in November, are important because they set the expectations against which markets will judge the credibility of the European Central Bank’s attempt to prove its banks can withstand another crisis without taxpayer help.

If official figures are far below independent estimates, authorities will struggle to convince markets the tests are robust enough, particularly given two previous rounds of EU tests that failed to reassure markets of banks’ health.

Banks have already raised over 500 billion euros from investors and taxpayers since the onset of the financial crisis, to bolster their balance sheets and help ward off a repeat of the 2008-09 financial crisis.

But the sector is again on edge ahead of the stress tests, because of the risk that regulators will call for even greater buffers against another credit crunch.

The new study, by Viral Acharya, a New York University professor and adviser to the European Systemic Risk Board (ESRB), and Sascha Steffen, of Berlin’s European School of Management and Technology, was circulated to banks, think tanks and the ESRB in recent weeks.

In their paper, Acharya and Steffen said eurozone banks would need up to 767 billion euros to bring their capital to the level seen by the Bank of England’s head of financial stability, Andrew Haldane, as needed for the banks to have withstood the last crisis.

The reference is to a 2012 speech where Haldane said the world’s largest banks would have needed equity equal to 7 percent of their total assets to guard against failure in the financial crisis.

But the 767 billion-euro figure only covers the 109 eurozone banks in the ECB’s exercise which disclose detailed data about their finances, so the figure across the 128 banks being tested would be even higher.

Banks across the globe will have to meet a 3 percent ratio under the new Basel III regulation, but some national authorities are pushing for a higher threshold.

“Balance sheets are not transparent enough for us to do what the ECB will do,” Steffen said. But their independence could be an advantage.

Acharya and Steffen, who singled out Belgium, Cyprus and France as countries whose banks could have significant shortfalls, along with Germany, also looked at how banks would be affected by a 40 percent fall in global stock markets over a six month period.


Credit to Shanghai Daily


China Preparing to Target U.S. Aircraft Carriers

China’s new hypersonic missile vehicle is primarily designed to target U.S. aircraft carriers, military expert Chen Hu told the state-run China Central Television (CCTV) in yet another admission of Beijing’s increasingly hostile geopolitical posturing.


The WU-14, a hypersonic glide vehicle which can penetrate missile defense systems by traveling at up to ten times the speed of sound, underwent its first test flight earlier this month.

Despite assurances by China’s defense ministry that the new vehicle was not aimed at any particular country, Chinese military expert Chen Hu told state media that the system, “can surely be used against US carriers in any region around the globe” and that it was “designed to strike large military targets including US aircraft carriers.”

Noting that the development of the vehicle was necessary in order to maintain the balance of power in East Asia, Chen said that its purpose is to prevent the United States from using its hypersonic weapons against China, adding that the Cold War-era doctrine of “mutually assured destruction” is guiding policy both in Washington and Beijing.

Last year, China reportedly sunk a mock U.S. aircraft carrier utilizing the DF-21D anti-ship missile, dubbed the “carrier killer,” during a wargame which took place in the Gobi Desert.

Bellicose rhetoric directed at the United States by China has intensified in recent months in light of heightened tensions over the disputed Senkaku Islands.

Last month, Beijing bragged that its first aircraft carrier combat task force, led by the inaugural Liaoning warship, matched anything the United States had to offer.

A lengthy editorial which appeared in Chinese state media last month explained how the Chinese military’s current reformation process was part of a move by President Xi Jinping to prepare the People’s Liberation Army for war in response to US aggression in the Asia Pacific, developments which have prompted “major changes” in China’s national security situation.

Beijing has also pontificated about China’s ability to attack US military bases in the Western Pacific, as well as releasing a map showing the locations of major U.S. cities and how they would be impacted by a nuclear strike launched from the PLA’s strategic submarine force.

Credit to Paul Joseph WatsonInfowars.com

Marc Faber Reduce Government by Fifty Percent Minimum

Mega Default In China Scheduled For January 31


On Friday, Chinese state media reported that China Credit Trust Co. warned investors that they may not be repaid when one of its wealth management products matures on January 31, the first day of the Year of the Horse.

The Industrial and Commercial Bank of China sold the China Credit Trust product to its customers in inland Shanxi province. This bank, the world’s largest by assets, on Thursday suggested it will not compensate investors,stating in a phone interview with Reuters that “a situation completely does not exist in which ICBC will assume the main responsibility.”

Zhenfu was undoubtedly desperate for money. One of its vice chairmen was arrested in May 2012 for taking deposits without a banking license, undoubtedly trying to raise funds through unconventional channels. 

 In any event, the company was permitted to borrow long after it should have been stopped—reports indicate that it had accumulated 5.9 billion yuan in obligations. Zhenfu, according to one Chinese newspaper account, has already been declared bankrupt with assets of less than 500 million yuan.There should be no mystery why this investment, known as “2010 China Credit-Credit Equals Gold #1 Collective Trust Product,” is on the verge of default. China Credit Trust loaned the proceeds from sales of the 3.03 billion-yuan ($496.2 million) product to unlisted Shanxi Zhenfu Energy Group, a coal miner. The coal company probably is paying something like 12% for the money because Credit Equals Gold promised a 10% annual return to investors—more than three times current bank deposit rates—and China Credit Trust undoubtedly took a hefty cut of the interest.

There has never been a default—other than one of timing—of a WMP, so the Credit Equals Gold product could be the first. If it is, it will edge out the WMP that invested in loans to Liansheng Resources Group, another Shanxi coal miner. Jilin Trust packaged Liansheng’s loans into a wealth management product sold by China Construction Bank , the country’s second-largest lender by assets, to its customers. Liansheng is in bankruptcy, and it looks like the WMP holders will not be repaid in full.

A WMP default, whether relating to Liansheng or Zhenfu, could devastate the Chinese banking system and the larger economy as well. In short, China’s growth since the end of 2008 has been dependent on ultra-loose credit first channeled through state banks, like ICBC and Construction Bank, and then through the WMPs, which permitted the state banks to avoid credit risk. 

Any disruption in the flow of cash from investors to dodgy borrowers through WMPs would rock China with sky-high interest rates or a precipitous plunge in credit, probably both. The result? The best outcome would be decades of misery, what we saw in Japan after its bubble burst in the early 1990s.


Credit to Forbes

ObamaCare’s Attack on the Elderly


In October of 2012, the Daily Mail exposed the highly disturbing realities of the Liverpool Pathway (LCP), the series of guidelines for treating terminally ill patients developed for Britain’s National Health Service (NHS).

The most egregious of those realities concerned cash incentives paid to hospitals to ensure a certain percentage of hospital patients would be put on the regime. As healthcare expert Besty McCaughey reveals, a similar horror show is occurring on this side of the Atlantic, courtesy of ObamaCare. Beginning the the same time the LCP scandal was being exposed, the Obama administration began awarding hospitals bonus points for spending the least amount of money on elderly patients. Even worse, the idea was sold to the elderly as a good thing during the 2012 presidential election campaign.

During that campaign, Obama promised seniors that $716 billion in Medicare cuts over the next decade, used to fund the $1.9 trillion in new healthcare spending that expanded Medicaid and created the healthcare exchanges, wouldn’t affect them. When Republican Presidential candidate Mitt Romney ran an ad attacking the cuts,Obama spokeswoman Lis Smith called it hypocritical. ‘The savings his ad attacks do not cut a single guaranteed Medicare benefit,’ she declared.

Much like everything else this administration contends, the devil is in the very deceiving details. While it’s technically true the cuts didn’t change the Medicare insurance benefits for those receiving them, $416 billion of that $716 billion in cuts were realized in ‘updates to fee-for-service payment rates.’ That was a euphemism used to obscure the reality that hospitals, doctors, hospice care, home care, and Advantage plans paid to care for seniors would be getting reduced payments.

Elderly Americans were supposed to believe those reduced payments would have no negative consequences whatsoever regarding the quality and/or availability of their healthcare.

This is utter nonsense, and there is data to prove it. As McCaughey further notes, research sponsored by the National Institute on Aging and RAND examined over two million elderly patients treated at 208 California hospitals from 1999 to 2008. Published in 2011, the research revealed that elderly patients treated in lower-spending hospitals received less care and had lower survival rates than those treated at higher-spending hospitals.
Cuts in Medicare payments to hospitals
The numbers are stark. According to the data,13,613 seniors with pneumonia, stroke, heart attacks and other common conditions who died at low-spending hospitals would have survived—and returned home—had they received treatment at higher-spending institutions. Those totals represent only the state of California, which contains about 10 percent of the Medicare population.

Similar cuts in Medicare payments to hospitals made in 1997 produced similar results. Over the course of four years, $40 billion was cut out of the Medicare program. As a result, one-third of America’s hospitals went from being profitable to losing money. Seniors treated for heart attacks at hospitals absorbing the largest cuts had a 6-8 percent greater chance of dying than those treated at other hospitals. Despite claims by ObamaCare defenders that reduced payments to hospitals eliminates ‘fraud, waste, and abuse,’ researchers concluded that hospitals actually reduced something else, namely nursing care, to cope with the shortfalls.

In 2011 testimony given to Congress, Richard Foster, Chief Actuary of Medicare and Medicaid Services for the Obama administration, revealed that the cuts to hospitals engendered by ObamaCare, which amount to $247 billion over ten years, could force as many as 40 percent of them to operate at a loss, and that as many as 15 percent could stop accepting Medicare altogether, even though the program is their largest source of revenue.

Foster also revealed something far more ominous. Because Medicare will eventually pay doctors less than they’re getting for the already low-paying Medicaid, and only about one-third of what they get paid for treating someone with private insurance, seniors will have even more trouble finding hospitals and doctors willing to treat them. As disquieting as that reality is, it will be exacerbated: ObamaCare bars doctors from providing their patients with necessary care for an extra fee. Many will simply fall through the cracks on the road to ‘better care for everyone,’ even as individual seniors bear the painful—or deadly—brunt of this leftist utopian fantasy.

And such cuts will affect far more than critical care. Quality of life procedures, such as knee and hip replacements, angioplasty, bypass surgery and cataract operations will also be pared back. Thus, seniors who have grown accustomed to the active lifestyles made possible by medical advancements may have to lower their expectations.

Callousness of the president
In 2009, President Obama admitted as much at a White House ‘town hall’ meeting to promote the healthcare bill. A woman named Jane Sturm spoke about her nearly 105-year-old mother, initially denied a pacemaker five years earlier by one doctor, due to her age. Sturm explained that another doctor, who saw the elderly woman’s ‘joy of life,’ gave her the procedure.

She asked the president to address that reality. ‘Outside the medical criteria,’ Sturm asked Obama, ‘is there a consideration that can be given for a certain spirit… and quality of life?’ Obama responded by talking about the waste that exists in the system ‘that’s not making anybody’s mom better’ including ‘loading up on additional tests or additional drugs that the evidence show is not going to improve care’ before coming to the conclusion that ‘maybe you’re better off not having the surgery, but taking a painkiller.’

Aside from the callousness of the president’s observation, it should be noted that loading up on additional tests or drugs is more familiarly known as practicing ‘defensive medicine,’ a reality exacerbated by potential litigation. Because trial lawyers are some of the Democratic Party’s main campaign supporters, it is no accident that the massive healthcare bill enacted solely by that party didn’t contain a single word about tort reform.

Furthermore, Obama is wrong. Currently Medicare pays hospitals an average of 91 cents on the dollar for the costs associated with caring for seniors. That’s a loss, not a profit. And peer-reviewed scientific research reveals that seniors who receive quality of life surgeries, such as a knee replacement to alleviate the pain associated with severe osteoarthritis, have a 50 percent higher chance of being alive five years after the operation than seniors who merely endure the condition. Thus in many cases seniors,are better off having the surgery.

Unfortunately, much like the ‘tick box’ treatment British seniors received until it was condemned as a ‘national disgrace,’ individual care matters less than the ‘greater good’ of containing costs. Thus, in addition to across-the-board cuts, hospitals will be forced to cope with an ObamaCare regulation called’ Medicare spending per beneficiary.’ Bonus points will be awarded to those institutions that spend the least on seniors, while those that don’t get demerits. Those spending calculations include up to 30 days of post-discharge treatments, such as physical therapy following surgery for a joint replacement.

In Britain, the LCP is being axed in favor of personal healthcare plans to address end-of-life issues. It is being done because the British government recognized the inevitable cruelty that occurs when treating the aged becomes little more than a numbers game. Yet, in America, we are moving in precisely the opposite direction, one bonus point or demerit, after another. For shame.

Credit to Canda Free Press