Wednesday, March 14, 2012


Four US banks fail Federal Reserve stress test including Citigroup, SunTrust, Ally Financial and MetLife


15 hours ago
15 hours ago
Four US financial institutions, including Citigroup, have failed stress tests designed to show they could withstand a financial shock.
The Federal Reserve said Citi, SunTrust, Ally Financial and MetLife failed to show they have enough capital to survive another serious downturn.
Citigroup is the third-largest US bank. The majority of the 19 tested passed.
All those tested are in a much stronger position than they were after the 2008 financial crisis, the Fed added.
The Fed tested the banks' ability to withstand a similar crisis that triggered a rise in unemployment to 13%, a 50% fall in share prices and a 21% drop in house prices.
Their strength is assessed by its Tier 1 capital ratio - assets held in reserve as a buffer against financial troubles.
The regulator said Citigroup had a Tier 1 capital ratio of 4.9%, with Ally Financial and SunTrust at 4.4% and 4.8% respectively.
MetLife had 6%, although it was measured slightly differently to the others.
"One problem (for Citi) is too much exposure in Europe," said Chris Lowe from FTN Financial in New York.
"It can shift its global focus, but obviously that's going to take time," he added.Tough
The banks with the best ratio were Bank of New York Mellon, at 13.1%, State Street on 12.5% and American Express at 10.8%.
"I think the tests are quite significant," said Matthew Bishop, US business editor of the Economist
I'm not convinced that they are any better at predicting the future than they were before”Matthew BishopThe Economist
"Even the banks that failed like Citigroup failed largely because they were planning to hand too much money back to investors... had they not handed any money back to investors, they probably would have passed."
The Federal Reserve has been conducting stress tests since 2009, but these were the first where results were made public.
The scenario was tougher than in previous years as the Fed wants to be sure US banks will be fit enough to meet new banking rules, known as Basel III, which come into force in 2014.
The results had an immediate impact on share prices, as a pass means the banks can increase shareholder dividends.
The Fed was expected to release the results of the tests on Thursday, but brought them forward after JP Morgan said on Tuesday it had passed the test.
JP Morgan's shares rose 7% after the news, while Citibank's fell 4%.
The bank had been expected to meet requirements and pay a dividend to shareholders.'Not convinced'
The Fed wants banks to show they could not only withstand a future crisis but could keep lending, unlike the freeze of the credit crunch of 2008, which deepened economic pain.
But experts remain sceptical about how effective these tests are in preparing banks for future crises.
"My bigger worry is that the Federal Reserve and other central banks completely failed to see the last banking crisis... and I don't necessarily feel comforted that they've guessed the worst case scenario accurately," Matthew Bishop of the Economist told the BBC.
"I'm not convinced that they are any better at predicting the future than they were before."
BBC
Israel develops its own bunker buster

Israel has developed an improved precision, bunker-burrowing weapon which Israeli Military Industries (IMI) unveiled on March 6. The 500-pound MPR-500 is an electro-optical (laser-guided) bomb that can penetrate double-reinforced concrete walls or floors without breaking apart.
The bomb was shown in action penetrating four reinforced concrete walls with fragmentation from the explosion limited to a radius of less than three meters.
The new weapon is designed as an upgrade for the US Mk82 in Israel Air Force stocks. “The lethality, precision… and relatively low weight of the new weapon,” say its manufacturers, “enable its use against multiple targets in a single pass.”
After blowing the first hole in the targeted underground site, the next bombs continue to extend and deepen it.
The MPR-500 bridges an operational gap between the 250-pound US GBU-39 small-diameter bomb, 1,000 of which were approved for sale to Israel and the 5,000-pound GBU-28 American super-bunker buster. DEBKAfile notes: The IMI’s presentation of the MPR-500 took place at the height of Israel’s argument with the Obama administration over the need for a near-term strike on Iran’s nuclear sites – especially those Tehran is busy transferring to fortified underground bunkers.
It attracted little attention because on the same day, Iran was invited by the Six Powers for nuclear negotiations, Tehran sent out its own invitation to UN nuclear inspectors to visit the suspect military site of Parchin (about which Iran has been hedging since) and the British cabinet received a top-secret intelligence briefing on the likelihood of an Israeli attack.
The Israeli Air Force is also reported to be planning to enlarge its Boeing-707 based aerial refueling tanker fleet, another key component in Israel’s ability to carry out an aerial strike against a target as distant as Iran. The expanded tanker fleet, by providing nearly 2 million pounds of fuel, would allow dozens of Israel F-15 and F-16 warplanes to carry more weapons on this mission.
Israeli officials have consistently challenged the claims of some experts that the lack the military capacity for a successful strike against Iran’s nuclear facilities.
Debkafile
Greece Has Defaulted - Which Country In Europe Is Next?
Well, it is official. The restructuring deal between Greece and private investors has been pushed through and the International Swaps and Derivatives Association has ruled that this is a credit event which will trigger credit-default swap contracts. The ISDA is saying that there are approximately $3.2 billion in credit-default swap contracts on Greek debt outstanding, and most analysts expect that the global financial system will be able to absorb these losses. But still, 3.2 billion dollars is nothing to scoff at, and some of these financial institutions that wrote a lot of these contracts on Greek debt are going to be hurting. This deal with private investors may have "rescued" Greece for the moment, but the consequences of this deal are going to be felt for years to come. For example, now that Greece has gotten a sweet "haircut" from private investors, politicians in Portugal, Italy, Spain and other European nations are going to wonder why they shouldn't get some "debt forgiveness" too. Also, private investors are almost certainly going to be less likely to want to loan money to European nations from now on. If they will be required to take a massive haircuts at some point, then why in the world would they want to lend huge amounts of money to European governments at super low interest rates? It simply does not make sense. Now that Greece has defaulted, the whole game is going to change. This is just the beginning.
The "restructuring deal" was approved by approximately 84 percent of all Greek bondholders, but the key to triggering the payouts on the credit-default swaps was the fact that Greece decided to activate the "collective action clauses" which had been retroactively inserted into these bonds. These collective action clauses force most of the rest of the bondholders to go along with this restructuring deal.
A recent article by Ambrose Evans-Pritchard explained why so many people were upset about these "collective action clauses"....
The Greek parliament's retroactive law last month to insert collective action clauses (CACs) into its bonds to coerce creditor hold-outs has added a fresh twist. These CAC's are likely to be activated over coming days. Use of retroactive laws to change contracts is anathema in credit markets.
If a government can go in and retroactively change the terms of a bond just before it is ready to default, then why should private investors invest in them?
That is a very good question.
But for now the buck has been passed on to those that issued the credit-default swaps. As mentioned above, the ISDA says that there are approximately $3.2 billion in Greek credit-default swaps that will need to be paid out.
However, that number assumes that a lot of hedges and offsetting swaps cancel each other out. When you just look at the raw total of swaps outstanding, the number is much, much higher. The following is from a recent article in The Huffington Post....
If you remove all hedges and offsetting swaps, there's about $70 billion in default-insurance exposure to Greece out there, which is a little bit bigger pill for the banking system to swallow. Is it possible that some banks won't be able to pay on their default policies? We'll find out.
Yes, indeed. We will find out very soon.
If some counterparties are unable to pay we could soon see some big problems cascade through the financial system.
But even with this new restructuring deal with private investors, Greece is still in really bad shape.
German Finance Minister Wolfgang Schaeuble told reporters recently that it "would be a big mistake to think we are out of the woods".
Even with this new deal, Greek debt is still projected to be only reduced to 120 percent of GDP by the year 2020. And that number relies on projections that are almost unbelievably optimistic.
In addition, there are still a whole host of very strict conditions that the Greek government must meet in order to continue getting bailout money.
Also, the upcoming Greek elections in just a few weeks could bring this entire process to an end in just a single day.
So the crisis in Greece is a long way from over.
The Greek economy has been in recession for five years in a row and it continues to shrink at a frightening pace. Greek GDP was 7.5 percent smaller during the 4th quarter of 2011 than it was during the 4th quarter of 2010.
Unemployment in Greece also continues to get worse.
The average unemployment rate in Greece in 2010 was 12.5 percent. During 2011, the average unemployment rate was 17.3 percent, and in December the unemployment rate in Greece was 21.0 percent.
Young people are getting hit the hardest. The youth unemployment rate in Greece is up to an all-time record of 51.1 percent.
The suicide rate in Greece is also at an all-time record high.
Unfortunately, there is no light at the end of the tunnel for Greece at this point. The latest round of austerity measures that are now being implemented will slow the economy down even more.
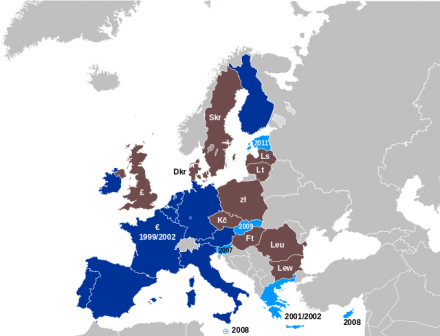
Sadly, several other countries in Europe are going down the exact same road that Greece has gone.
Investors all over the globe are wondering which one will be the "next Greece".
Some believe that it will be Portugal. The following is from a recent article in The Telegraph....
"The rule of law has been treated with contempt," said Marc Ostwald from Monument Securities. "This will lead to litigation for the next ten years. It has become a massive impediment for long-term investors, and people will now be very wary about Portugal."
Right now, the combination of all public and private debt in Portugal comes to a grand total of 360 percent of GDP.
In Greece, the combined total of all public and private debt is about 100 percentage points less than that.
So yes, Portugal is heading for a world of hurt. The following is more about Portugal from the recent Telegraph article mentioned above....
Citigroup expects the economy to contract by 5.7pc this year, warning that bondholders may face a 50pc haircut by the end of the year. Portugal's €78bn loan package from the EU-IMF Troika is already large enough to crowd out private creditors, reducing them to ever more junior status.
So why should anyone invest in Portuguese debt at this point?
Or Italian debt?
Or Spanish debt?
Or any European debt at all?
The truth is that the European financial system is a house of cards that could come crashing down at any time.
German economist Hans-Werner Sinn is even convinced that the European Central Bank itself could collapse.
There is a Der Spiegel article that everyone out there should read. It is entitled "Euro-Zone Central Bank System Massively Imbalanced". It is quite technical, but if this German economist is correct, the implications are staggering.
The following is from the first paragraph of the article....
More than a year ago, German economist Hans-Werner Sinn discovered a gigantic risk on the balance sheets of Germany's central bank. Were the euro zone to collapse, Bundesbank losses could be half a trillion euros -- more than one-and-a-half times the size of the country's annual budget.
So no, the European debt crisis is not over.
It is just getting warmed up.
Get ready for a wild ride.
Economic Collapse
Tuesday, March 13, 2012
Subscribe to:
Posts (Atom)